TradingView strategies simulate orders, while alerts can send signals to an external execution system. Connecting a broker in TradingView's trading interface does not automatically route Pine strategy orders to that broker. A live automation workflow needs a compatible receiver, explicit order mapping and monitoring.
A TradingView stop-loss and take-profit indicator calculates or draws levels. It does not place protective orders merely because lines appear on the chart. An alert, a simulated strategy exit, and an accepted broker order are separate steps, each with its own setup.
NinjaTrader's Order Flow VWAP plots a volume-weighted price reference and deviation bands. Its values depend on the reset interval, trading-hours template, calculation resolution, and available history. Those settings must match before two VWAP charts—or a chart and a strategy—can be meaningfully compared.
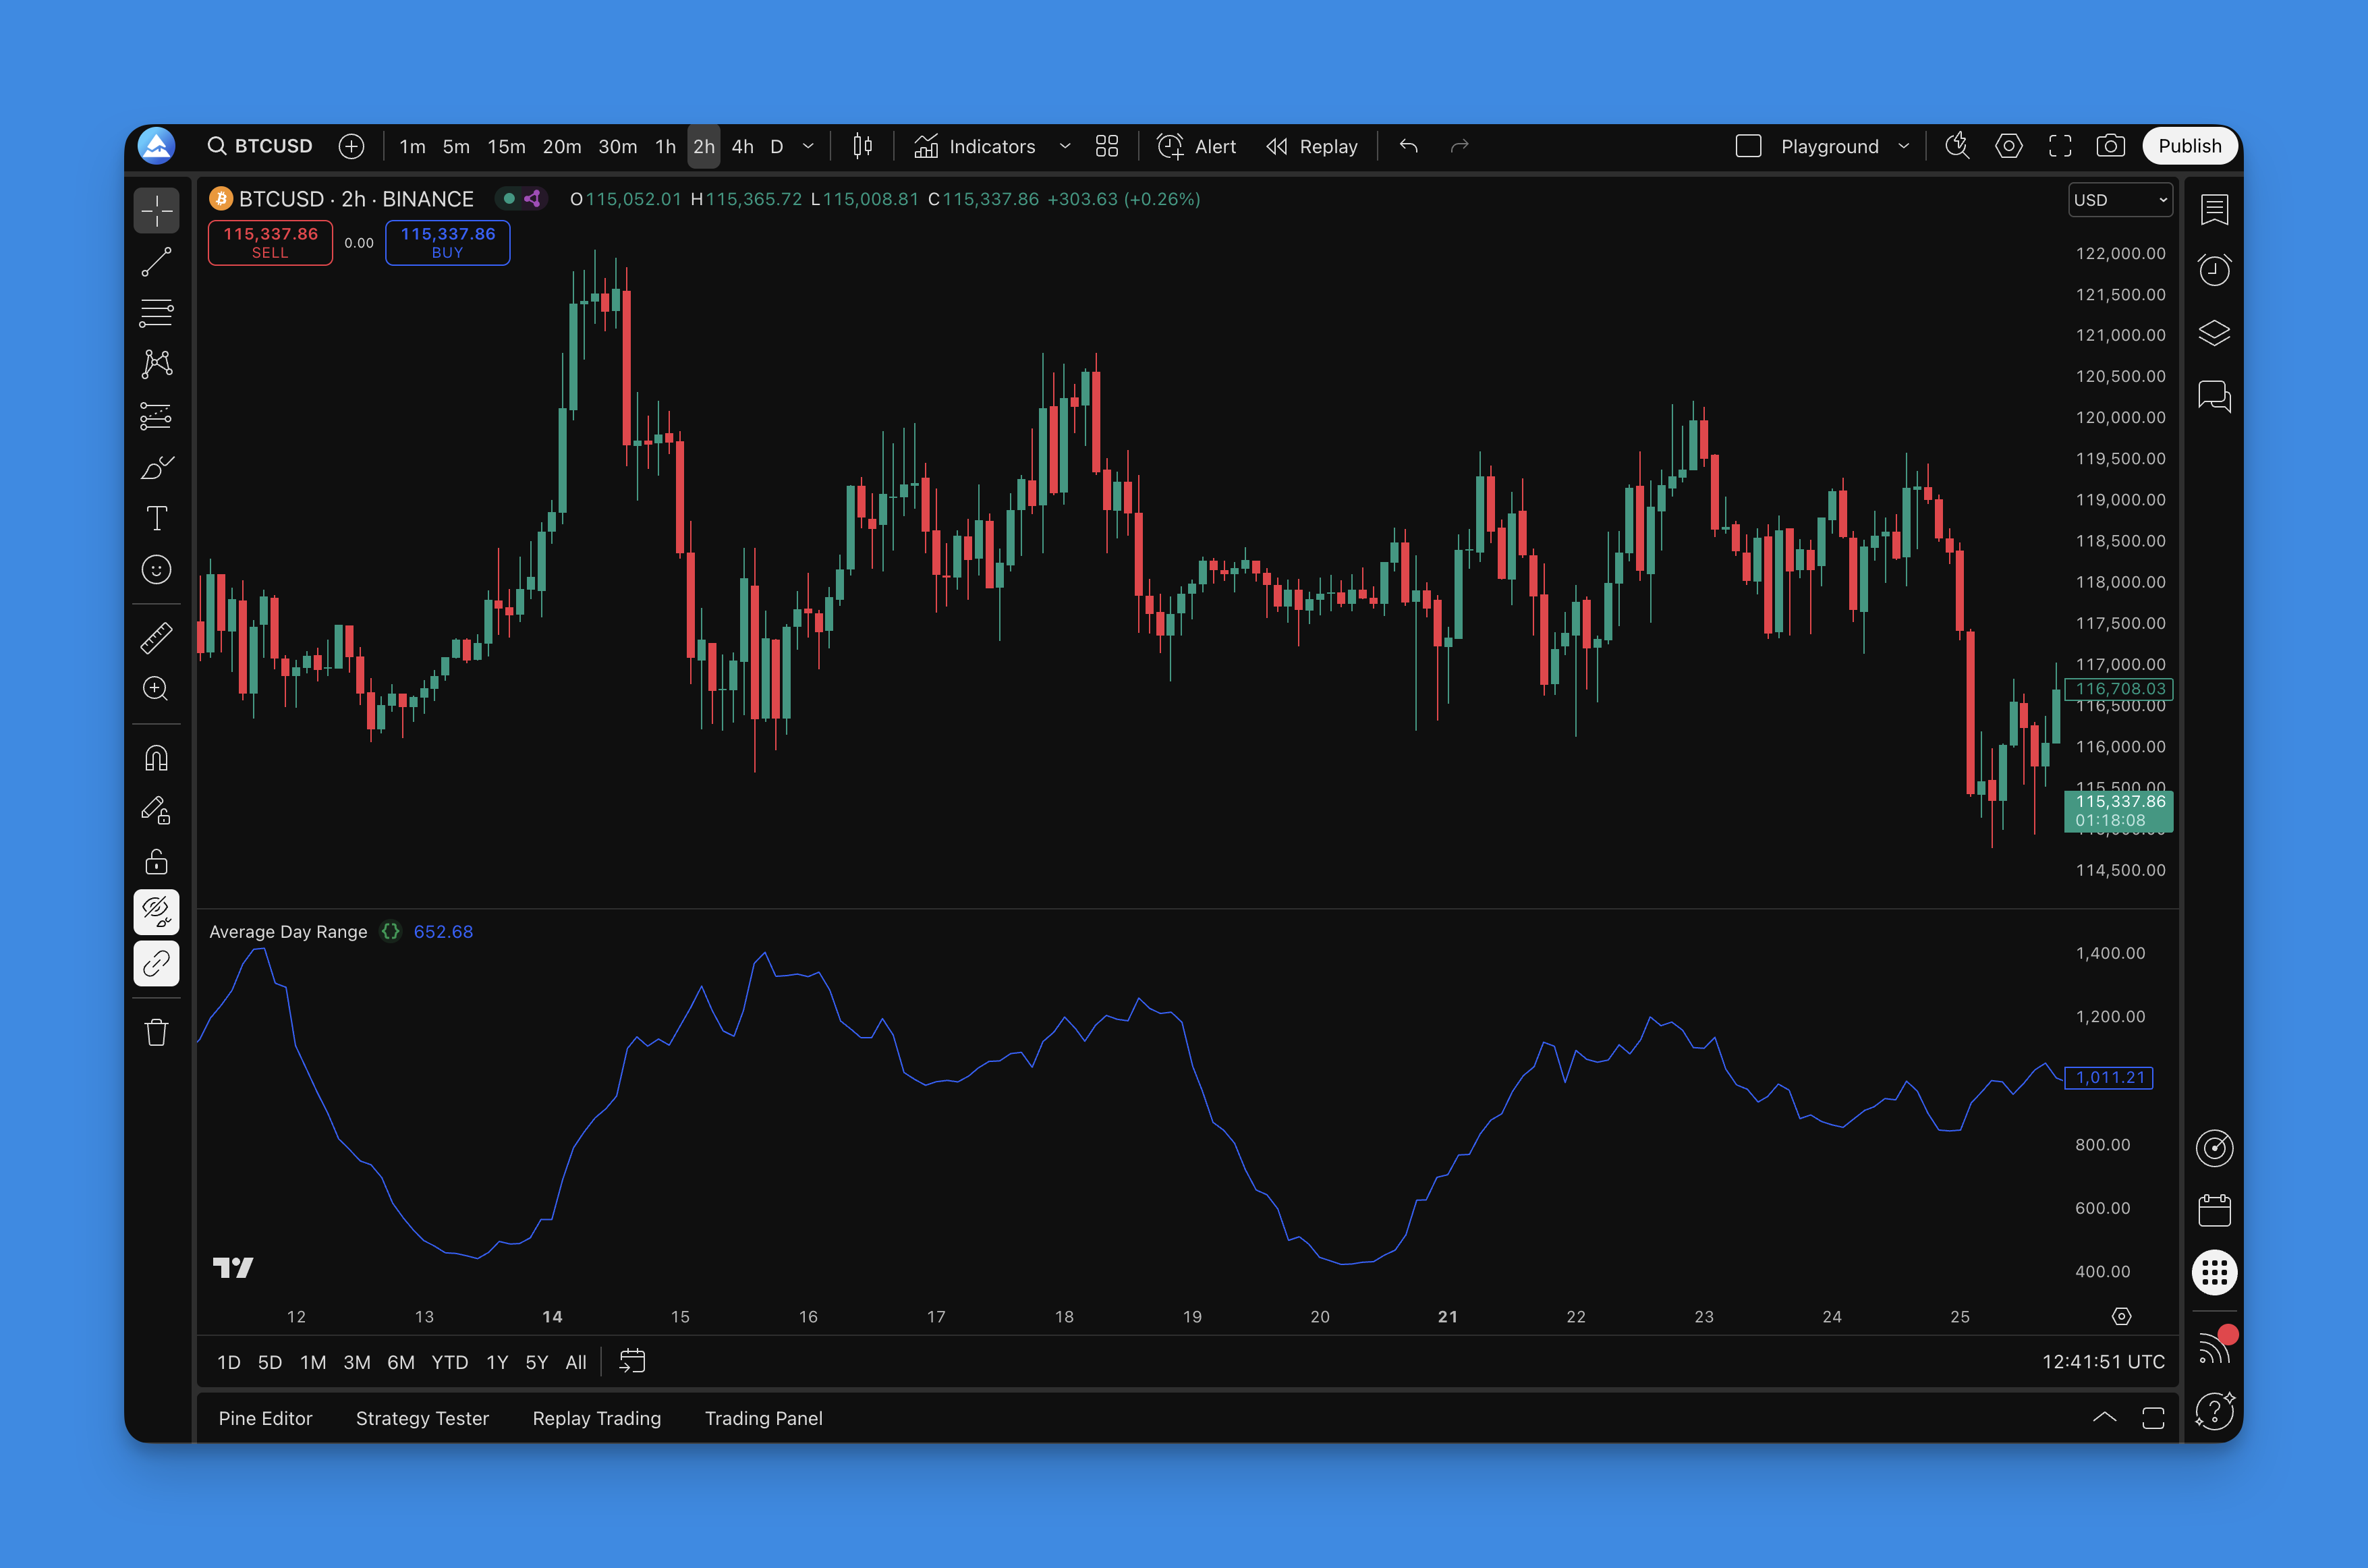
Average Day Range (ADR) is an average of daily high-minus-low ranges. It provides historical range context, not a prediction of the next session's direction or maximum move. The data interval matters: averaging five-minute bar ranges is not the same as averaging daily ranges.
Converting MQL4 to MQL5 means preserving a program's intended behavior on MetaTrader 5, not merely renaming functions until it compiles. The main migration risks are data timing, indicator access and the relationship between orders, deals and positions.
Start with a concrete reason to migrate, such as a broker or platform requirement. This guide does not establish a universal MT4 shutdown deadline or a fixed speed advantage for converted programs.
The Awesome Oscillator (AO) subtracts a 34-bar simple average of midpoint prices from a 5-bar average. It describes the difference between two historical price averages. Its sign and its bar color answer different questions, and neither guarantees a future price move.
An indicator displays calculations or signals. To measure trading performance, you must add explicit entry, exit, sizing and execution rules. TradingView supports manual historical inspection through Bar Replay and automated simulation through Pine strategies in Strategy Tester. Those workflows answer different questions.
Backtesting.py is an open-source Python framework for simulating trading rules on historical data. It is useful for inspecting a single instrument's signals and trades. The examples below demonstrate its API; they do not establish that a moving-average crossover is profitable or suitable for live trading.
Backtesting.py and Backtrader run Python simulations; Pineify helps generate Pine Script for TradingView. The useful choice depends on the data, portfolio model and development workflow you need. No controlled performance benchmark or first-hand AAPL comparison is established here.
A backtesting framework should be evaluated against the strategy's execution requirements. Backtesting.py offers a Python simulation API; Backtrader provides an event-driven engine with multiple feeds and broker models; Pineify generates Pine Script and supports TradingView research workflows. Pineify is not a Pine-to-Python portfolio execution bridge.