QuantConnect backtesting runs algorithm rules through the LEAN engine using historical data and configured execution models. The engine provides a framework for reproducible simulations; the realism of a particular result depends on the data, timestamps, brokerage settings, and strategy logic. The example is an implementation demonstration, not performance evidence.
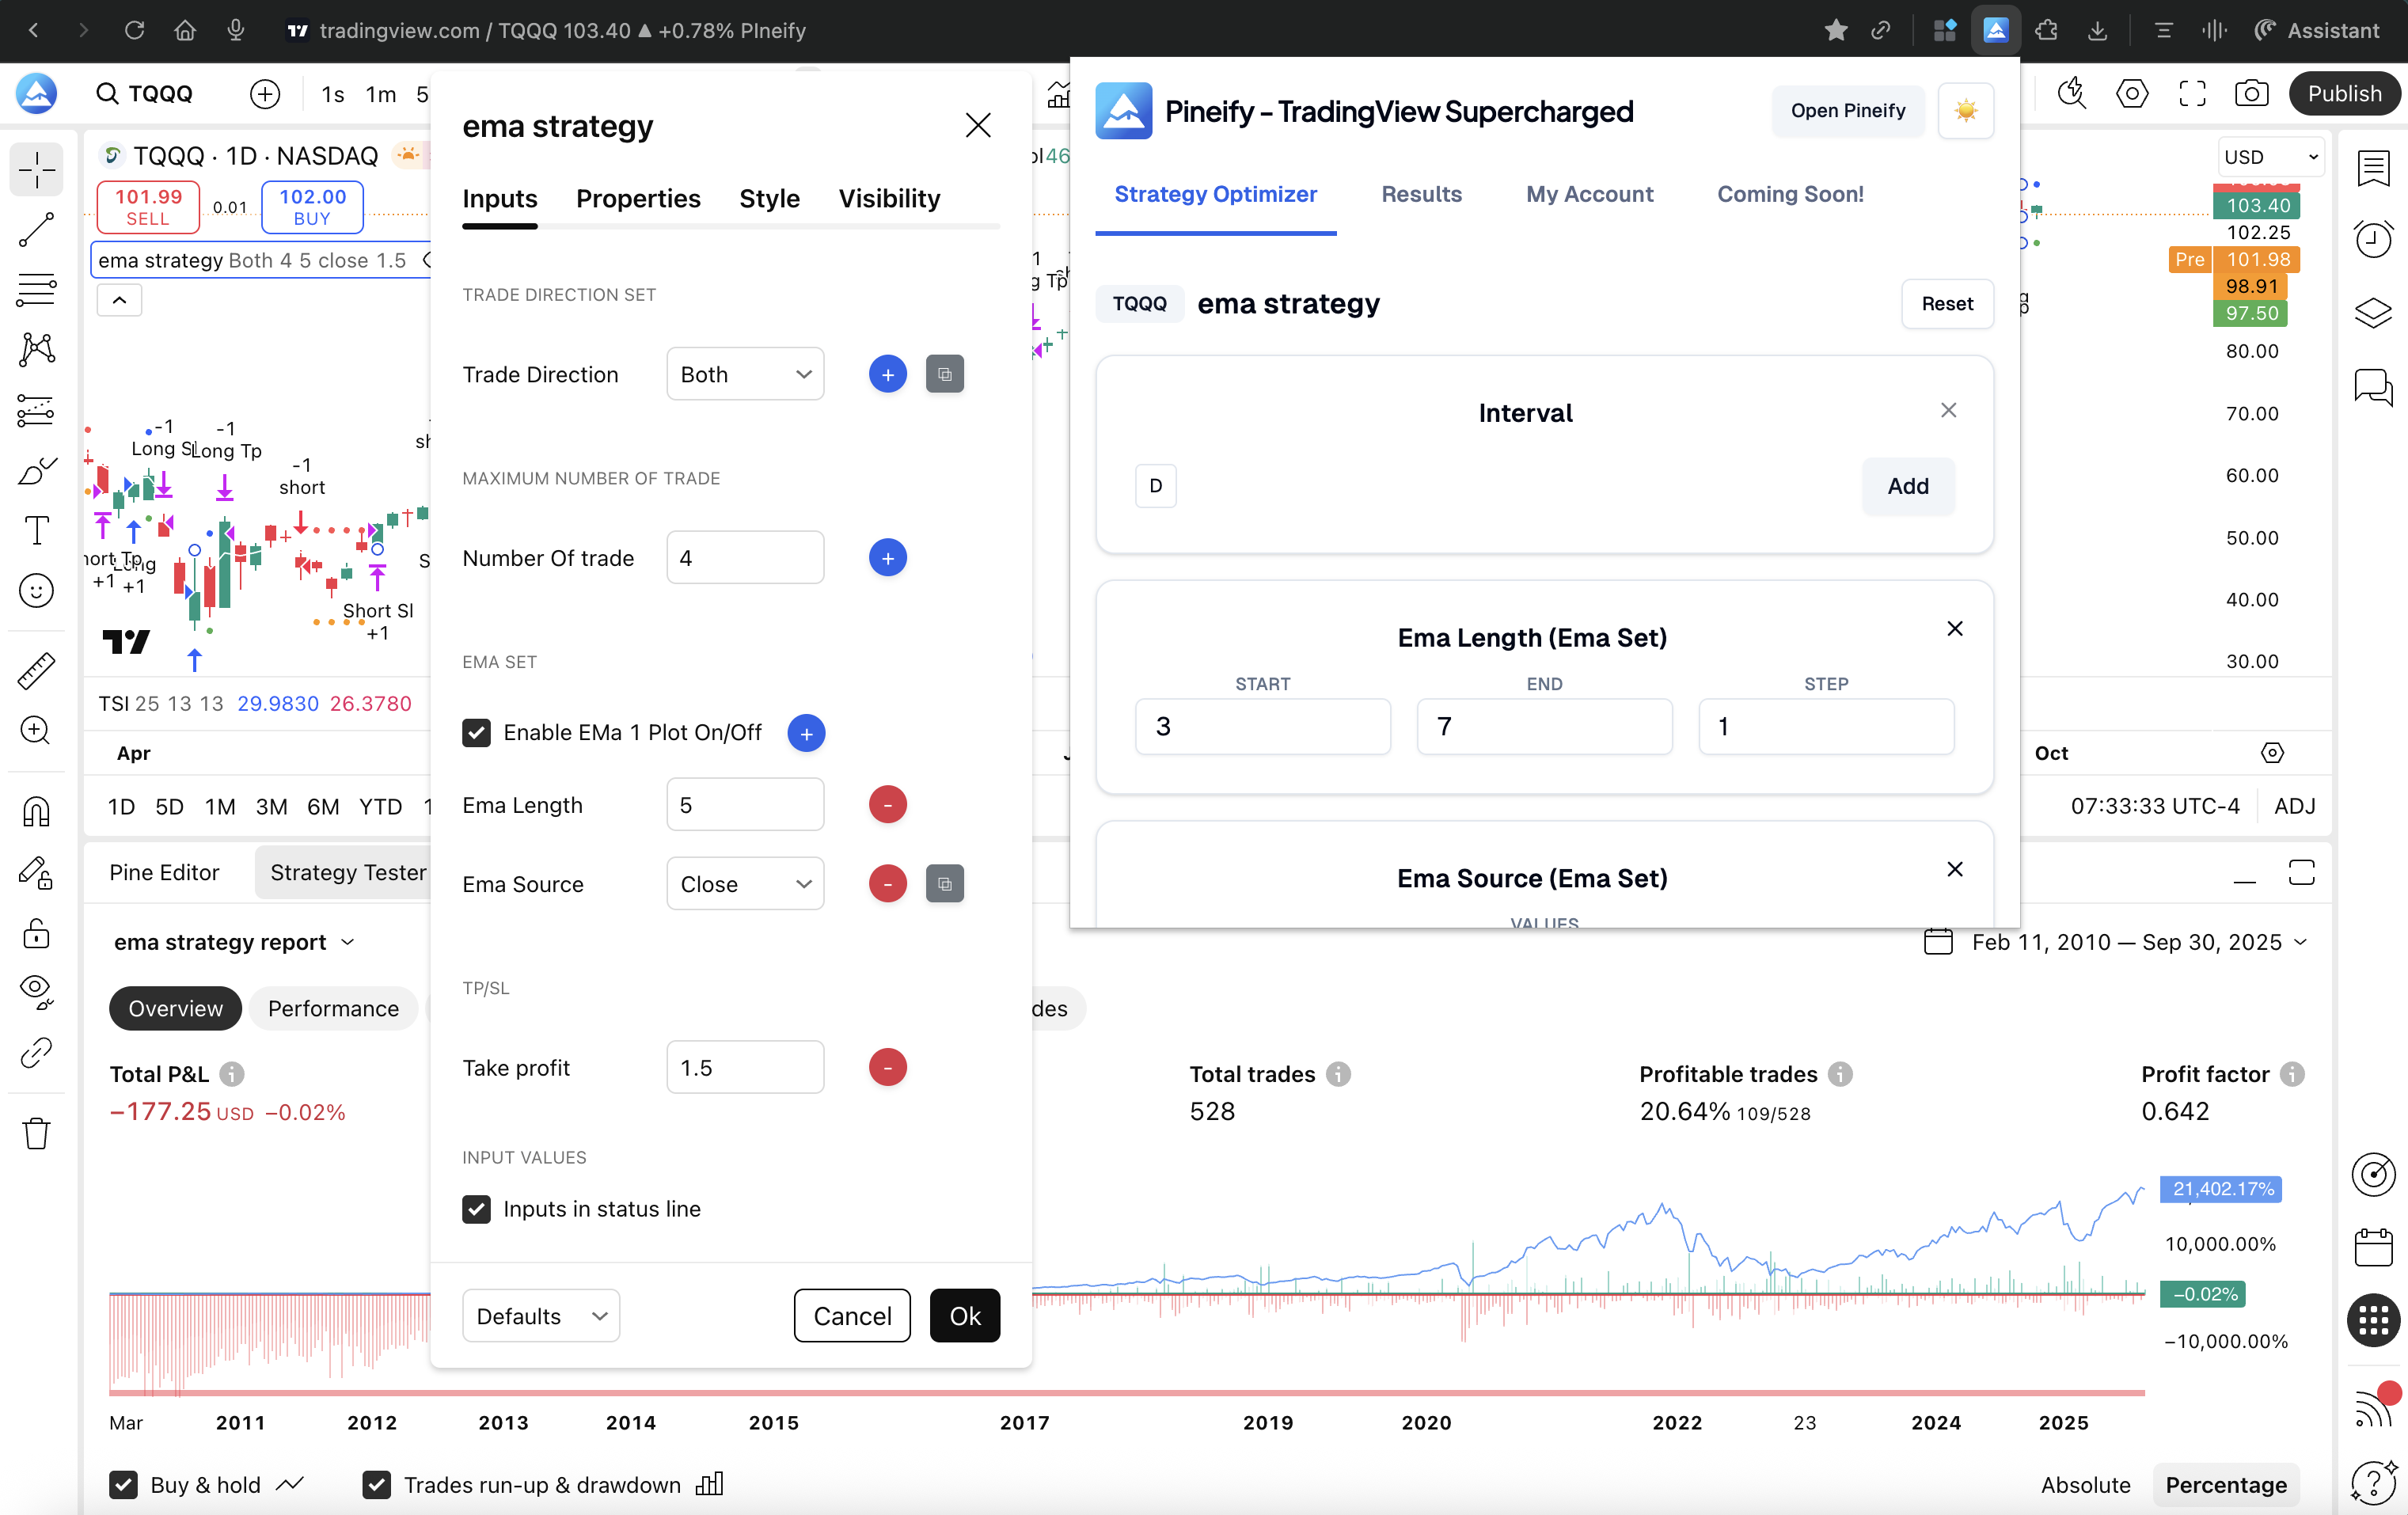
Pineify's Strategy Optimizer automates parameter changes and result collection in an open TradingView chart. QuantConnect provides optimization workflows for LEAN algorithms. The relevant choice is whether you want to search the inputs of an existing Pine strategy or develop and evaluate an algorithm in LEAN.
QuantConnect, Backtrader, and Pineify cover different parts of a trading-development workflow. QuantConnect provides a LEAN-based research and execution environment. Backtrader is a Python framework whose environment and integrations you manage. Pineify helps create code and analyze or optimize TradingView strategy workflows. A useful comparison separates code creation, historical evaluation, and live operation.
The hosted Quantopian service closed in late 2020, but its open-source projects remain relevant to legacy strategy code. Recovering that code requires separating the original service, the Zipline engine, the datasets, and the analysis libraries. Installing a library does not recreate the former hosted environment.
Quantower and TradingView both provide charting and trading workflows, but the useful comparison is your broker connection, data entitlement, order controls, and device requirements. This article does not report a measured latency advantage or claim that one platform reproduces live fills more accurately.
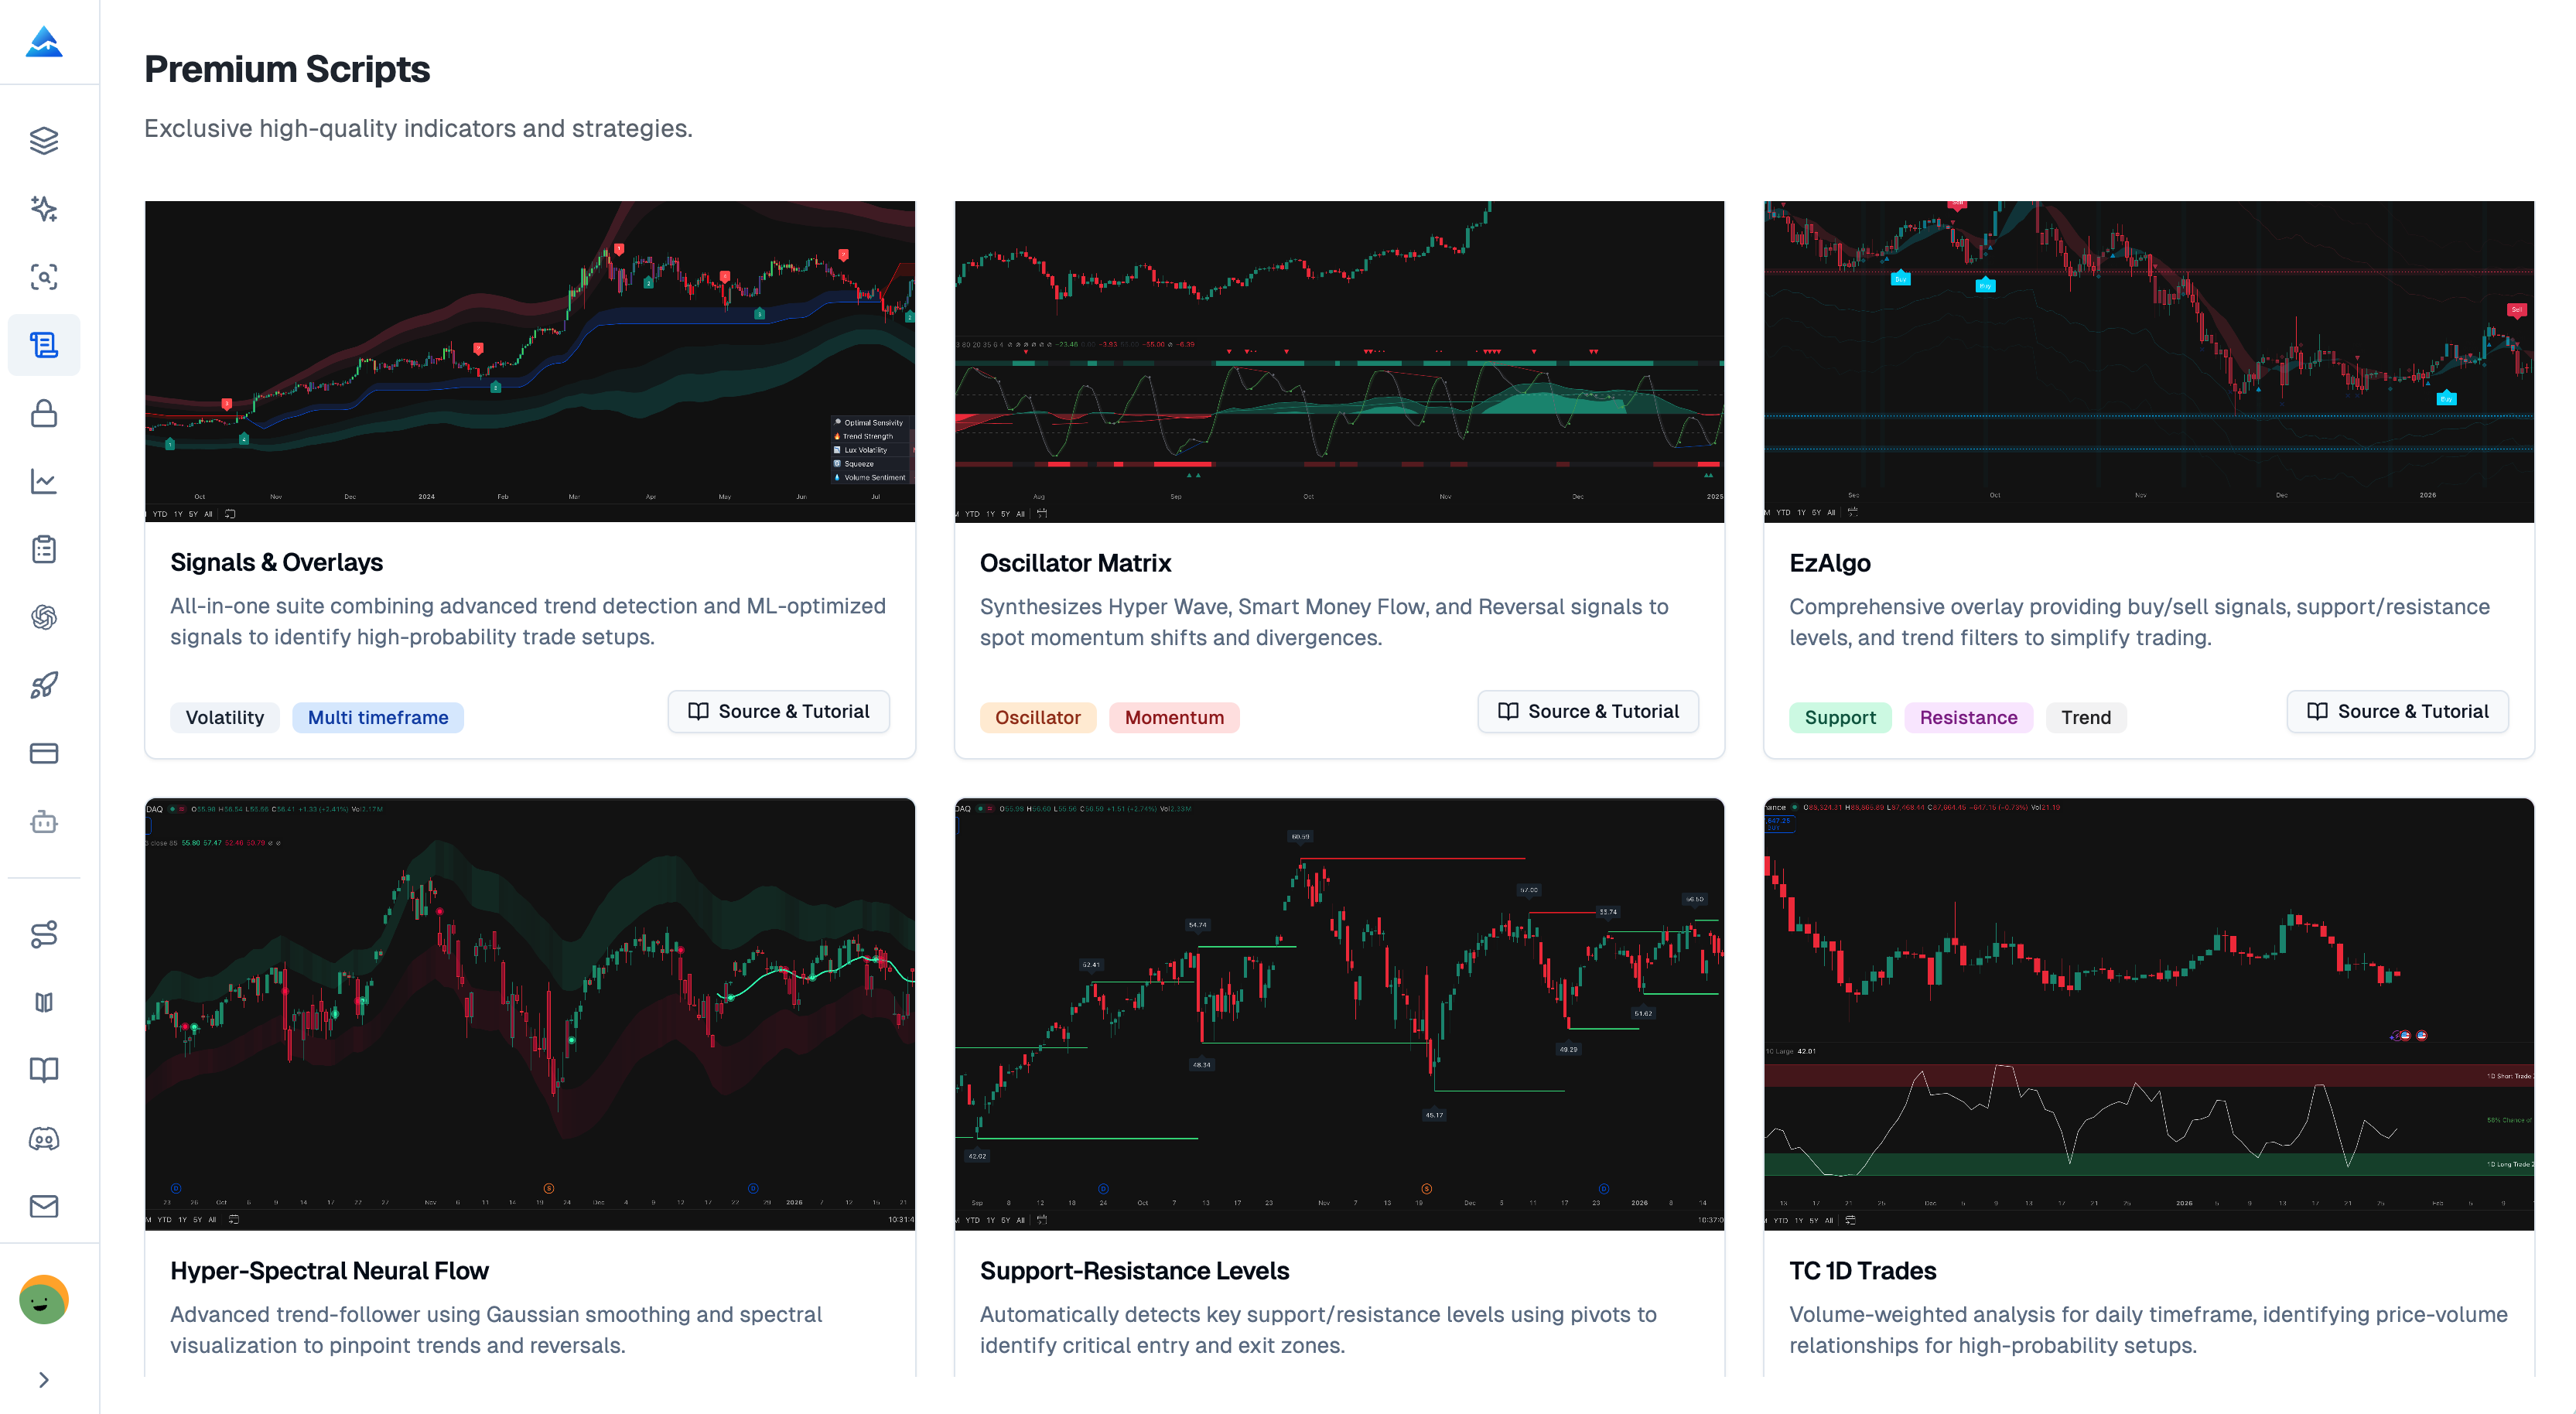
Quantpedia helps users research systematic trading ideas. Pineify Premium Scripts provides a catalog with access to script source and tutorials for eligible accounts. The distinction is the work you need next: investigating a research claim, inspecting an implementation, or testing a specific rule on TradingView.
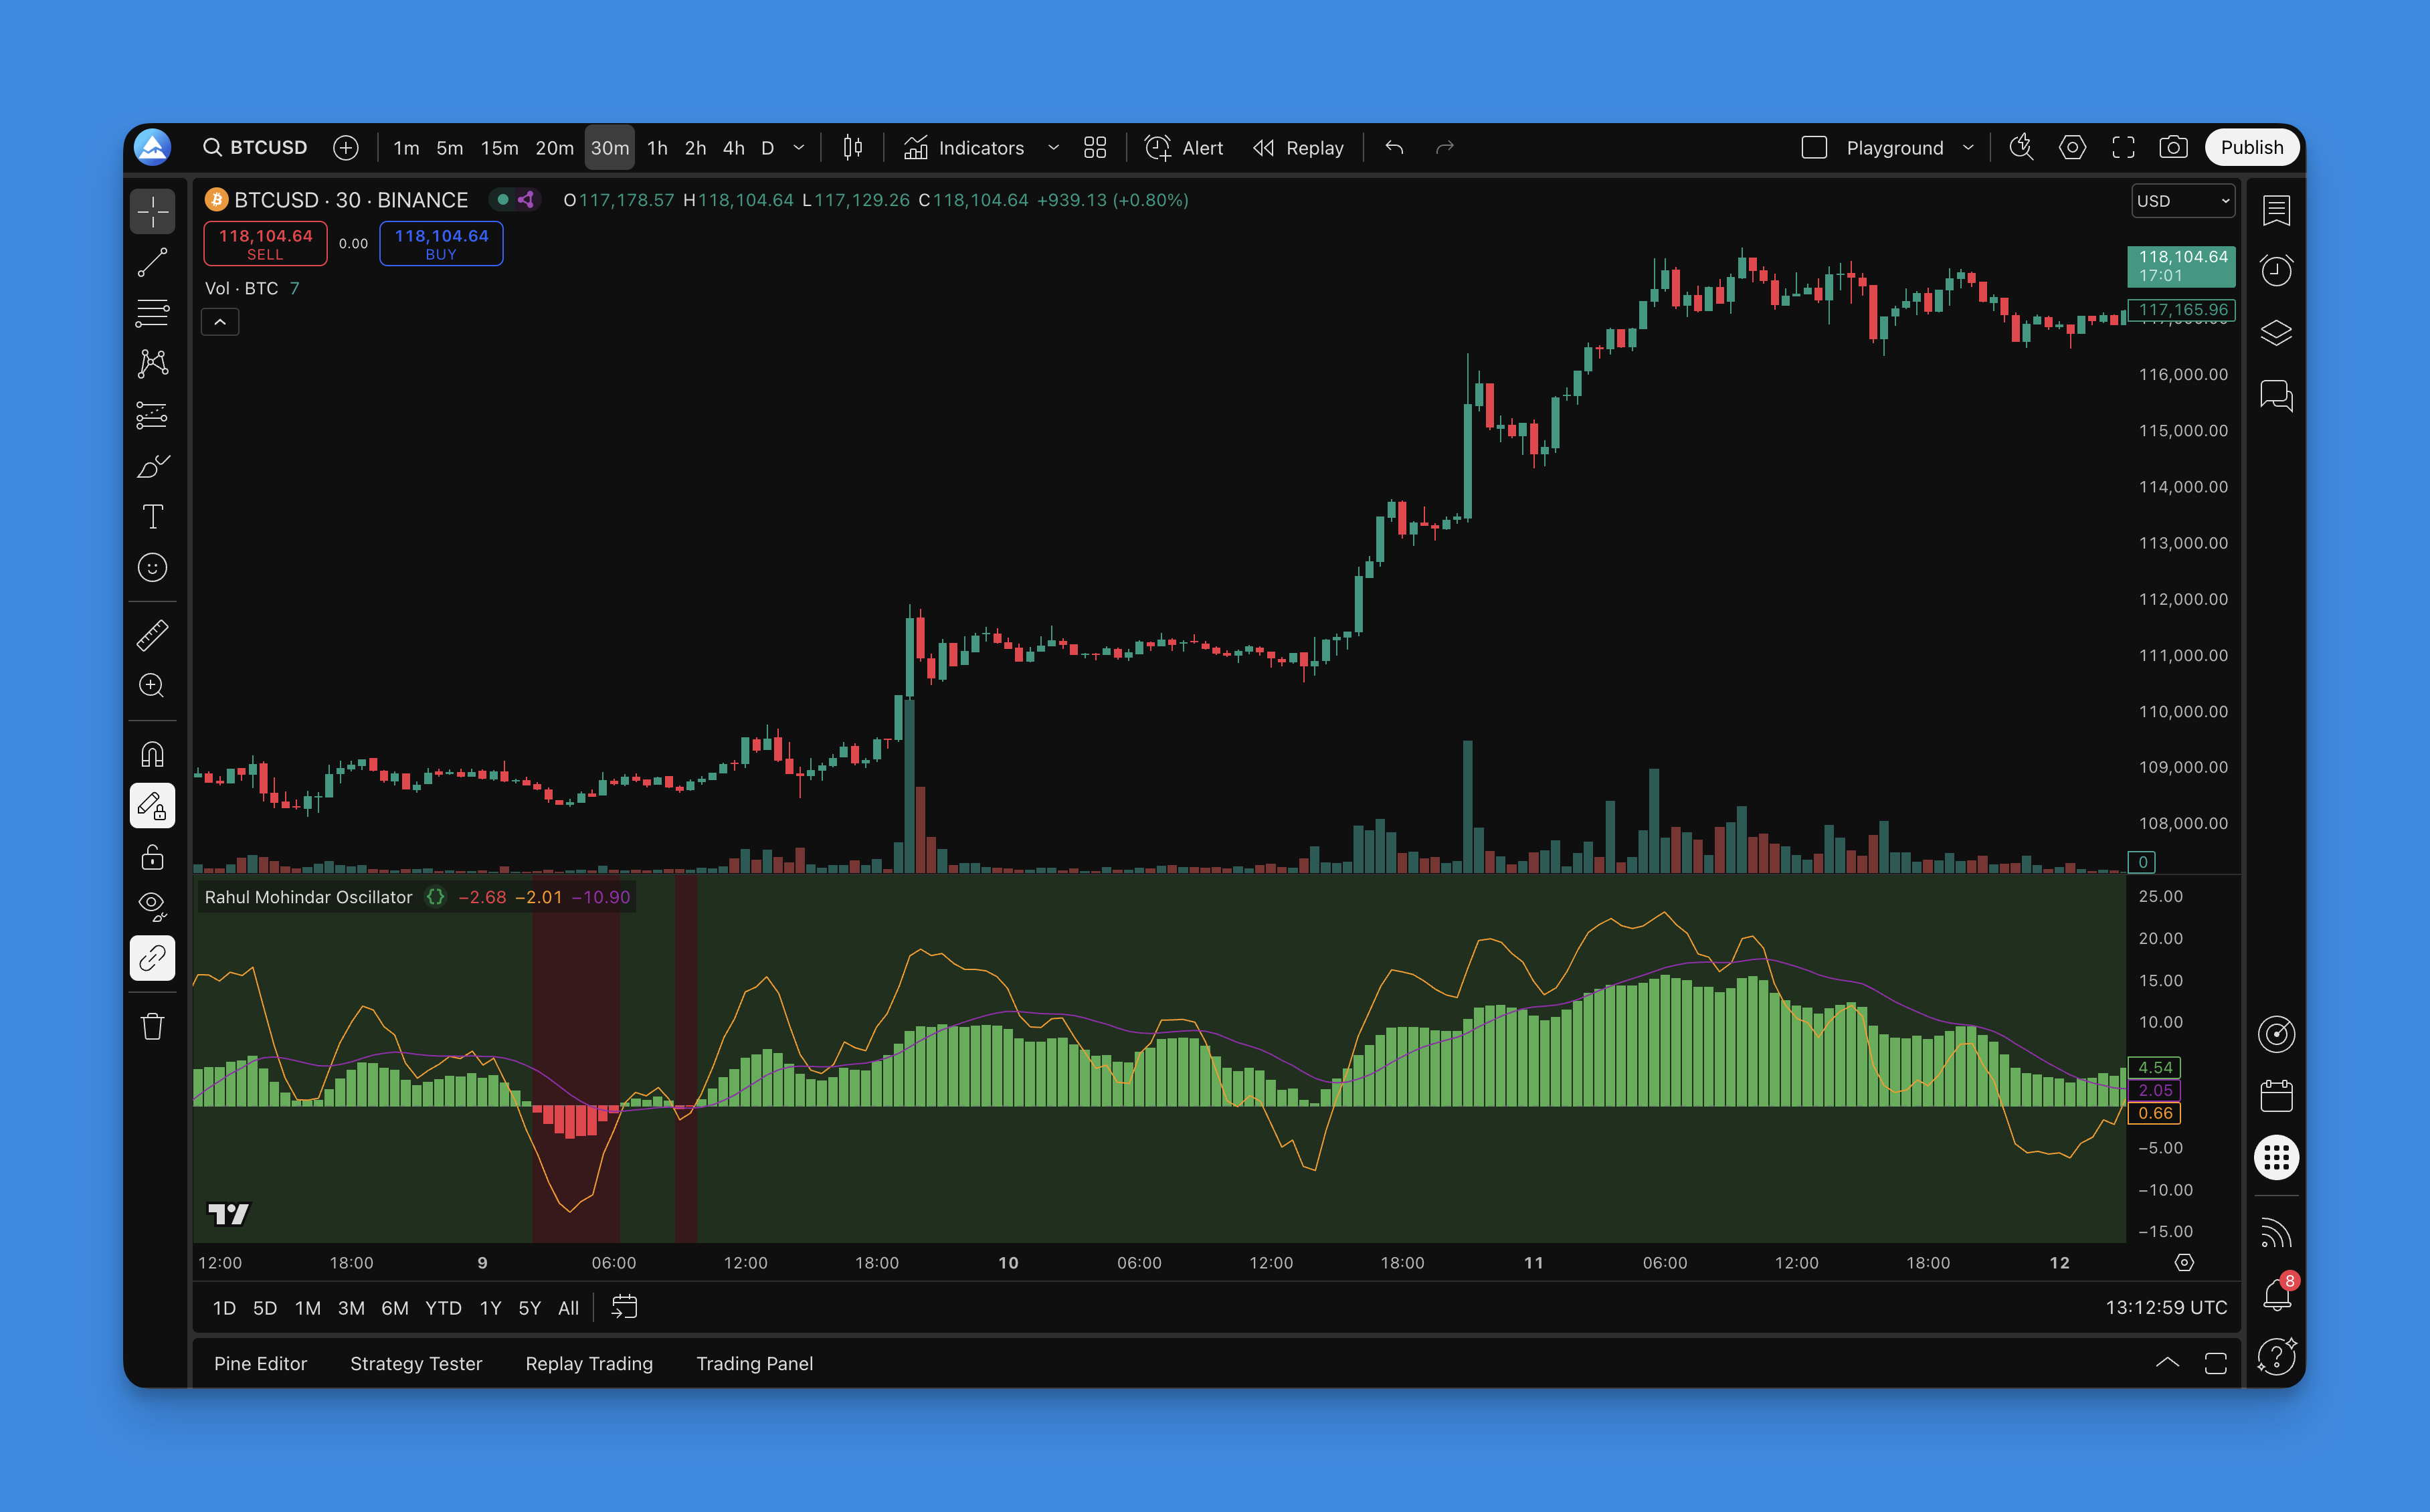
The Rahul Mohindar Oscillator (RMO) combines a smoothed, range-normalized price measure with trend and crossover outputs. This guide describes Pineify's implementation so you can identify its inputs and test a clearly defined rule. It does not report personal trades or a verified win rate.
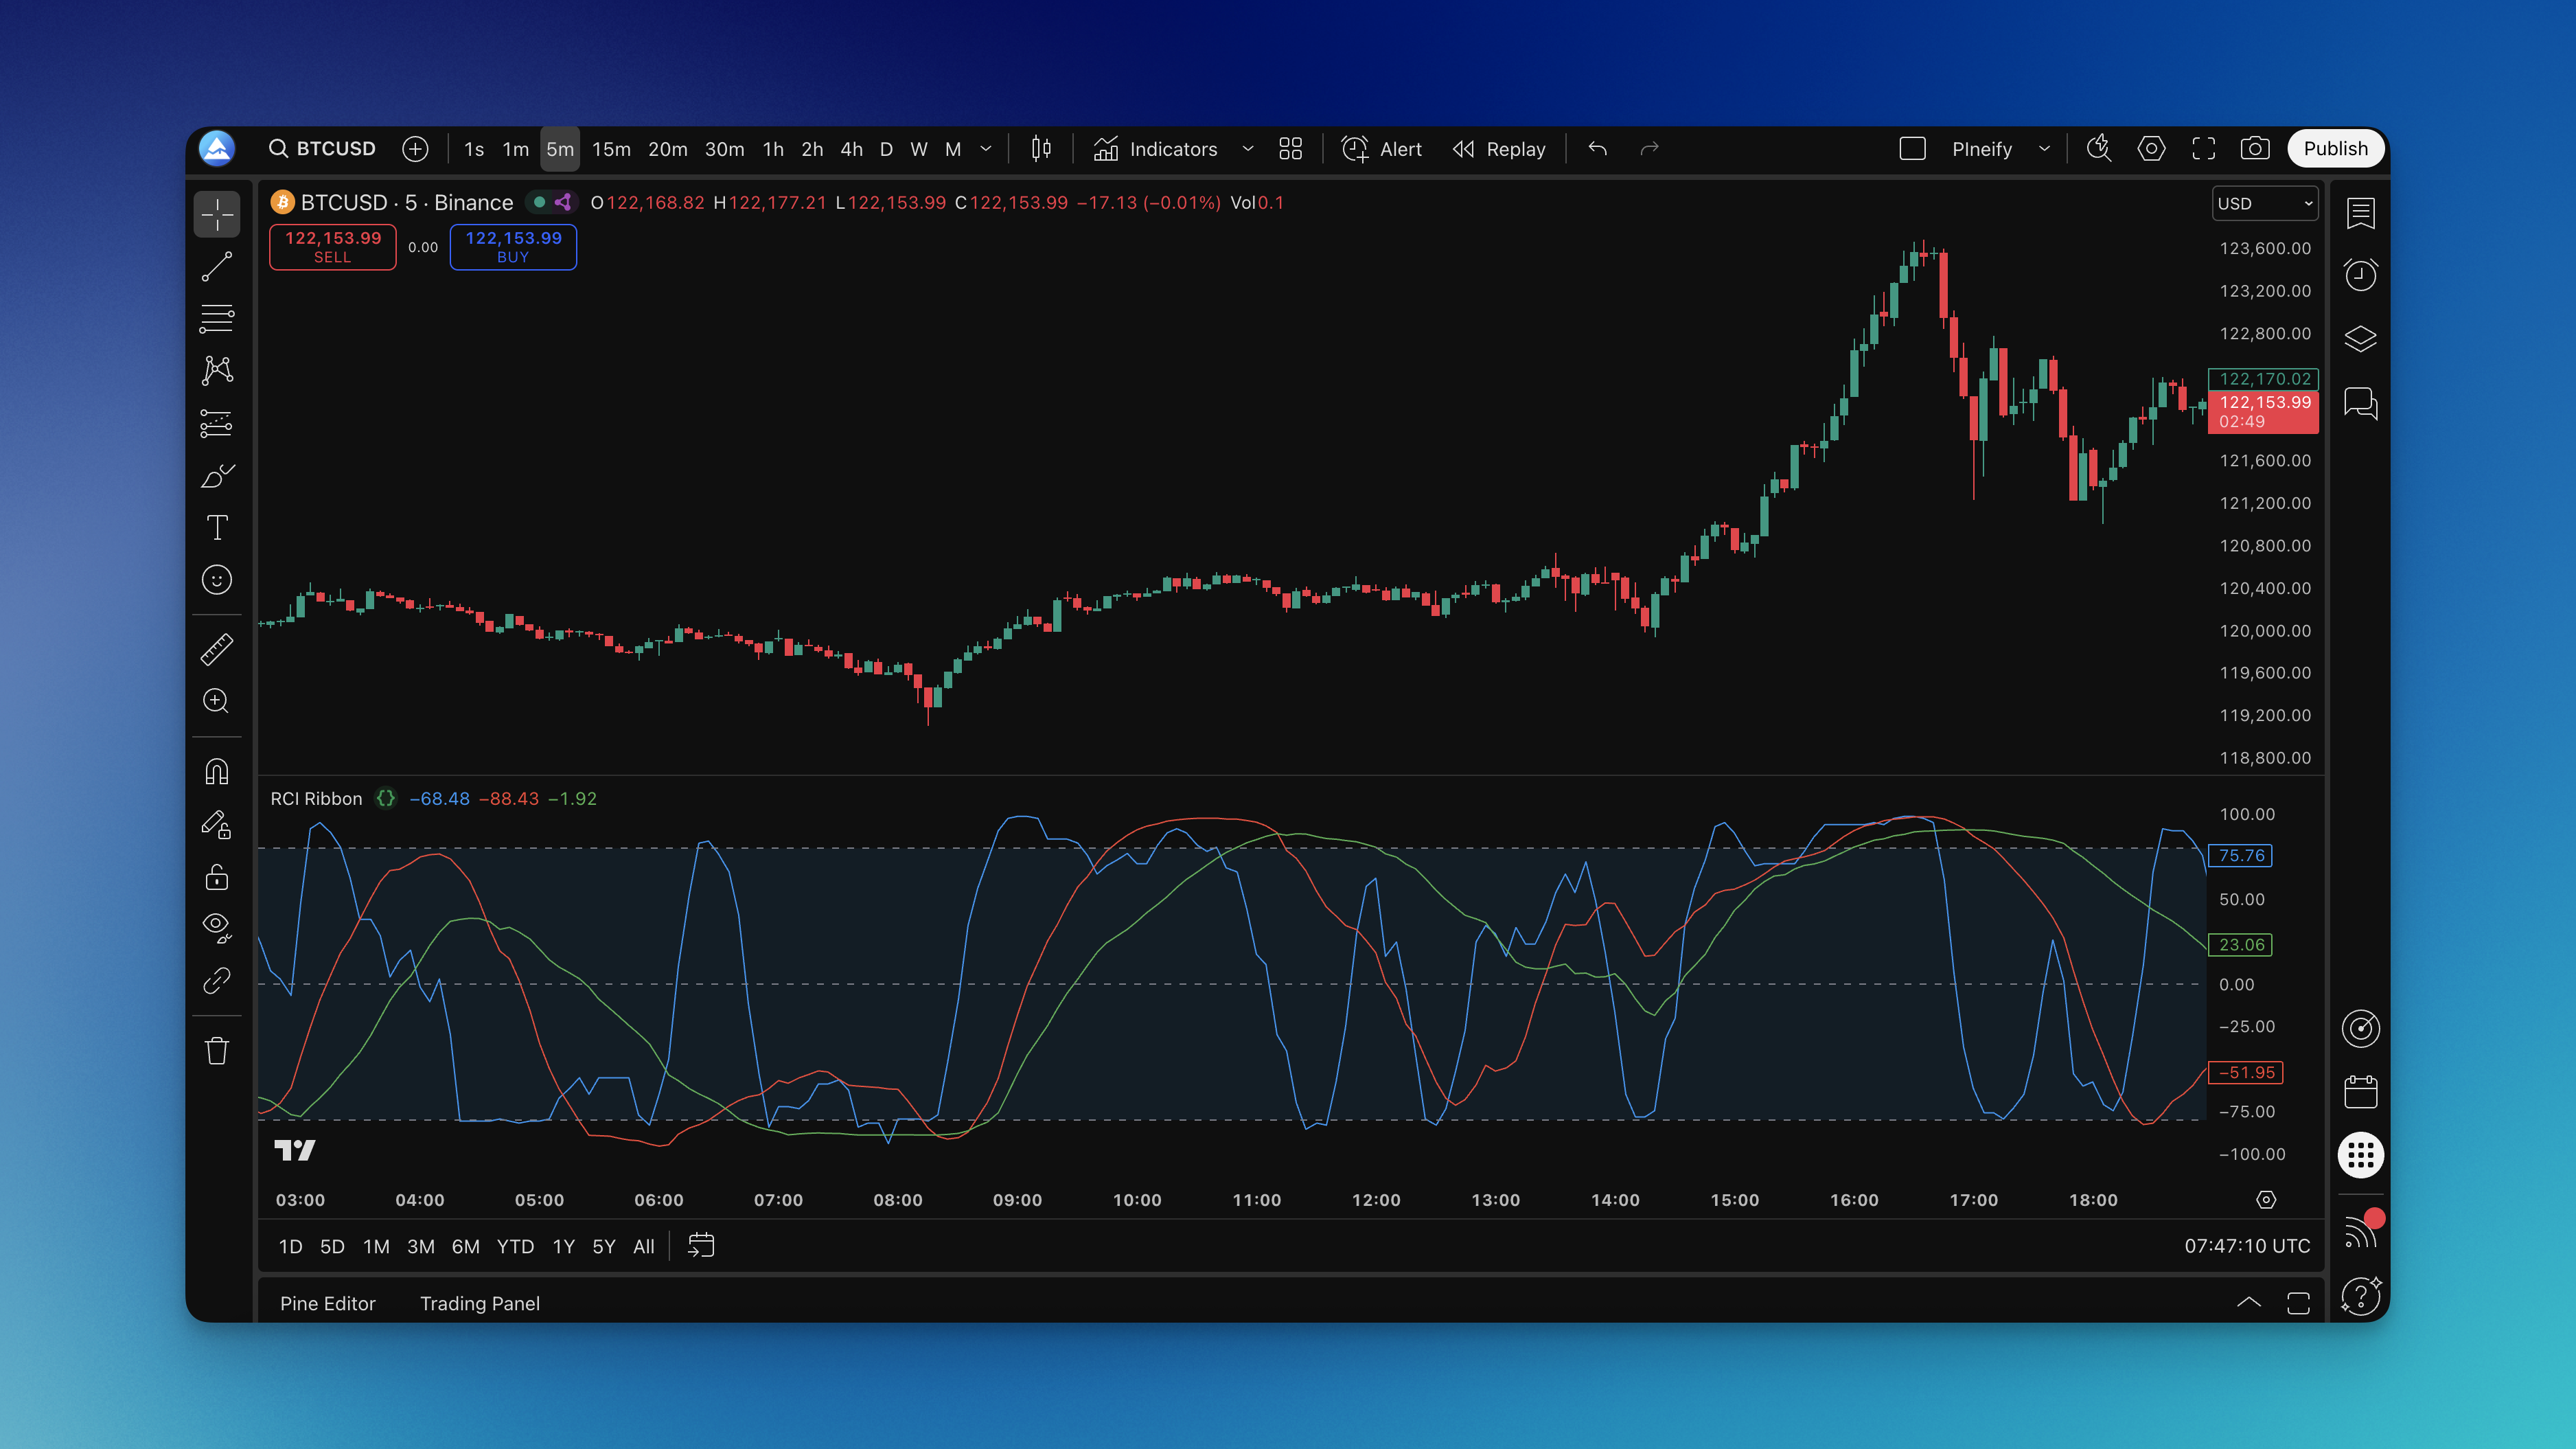
Pineify's RCI Ribbon calculates Rank Correlation Index values over three lookback lengths on the same source series. Its defaults are 10, 30, and 50 bars. Those are three windows on the selected chart data, not automatically three independently requested timeframes.
The Relative Strength Index (RSI) compares smoothed upward and downward price changes. It helps describe recent momentum; it does not establish that an overbought market must fall or an oversold market must rise.
The Relative Vigor Index (RVI) compares smoothed close-minus-open movement with smoothed high-minus-low range. Pineify labels this indicator RVGI. It oscillates around zero; it is not a 0 to 100 oscillator with a 50 midpoint or 80/20 overbought and oversold levels.