Track NVDA Options Flow: Contracts, Sentiment, and Earnings Context

NVDA options flow describes reported trading activity in NVIDIA option contracts. It can help organize questions about expiry, strike, premium, and execution conditions. It does not disclose a trader's complete position or prove that a large transaction predicts the next stock move.
Start with the contract, not the headline amount
Record the underlying ticker, call or put, expiry, strike, timestamp, and reported premium. For a standard equity option, premium is generally option price times contracts times the contract multiplier, commonly 100. Adjusted contracts can have different deliverables, so verify the contract specification rather than assuming every historical NVDA series is identical.
A dollar threshold is a filter for size, not a classification of the owner. A large trade may be an institution, a market maker, a hedge, a closing order, or one leg of a larger transaction. A strike is a contract term, not necessarily the trader's stock-price target.
| Observation | Question it supports | Conclusion it cannot establish alone |
|---|---|---|
| High premium | How large is the reported transaction? | Who traded or how strongly they believe a forecast |
| Sweep or multi-exchange activity | How was the order executed? | Whether it will be profitable |
| Volume above open interest | Is turnover large relative to existing positions? | That every contract opened a new position |
| Near expiry | How soon can time decay and exercise matter? | That the trader expects a particular earnings result |
| High implied volatility | How expensive is optionality under the pricing model? | The direction of the next stock move |
The Options Industry Council's explanation of open interest emphasizes that both counterparties' opening or closing activity matter. Intraday volume alone cannot resolve that question.
Read Pineify sentiment as a classification rule
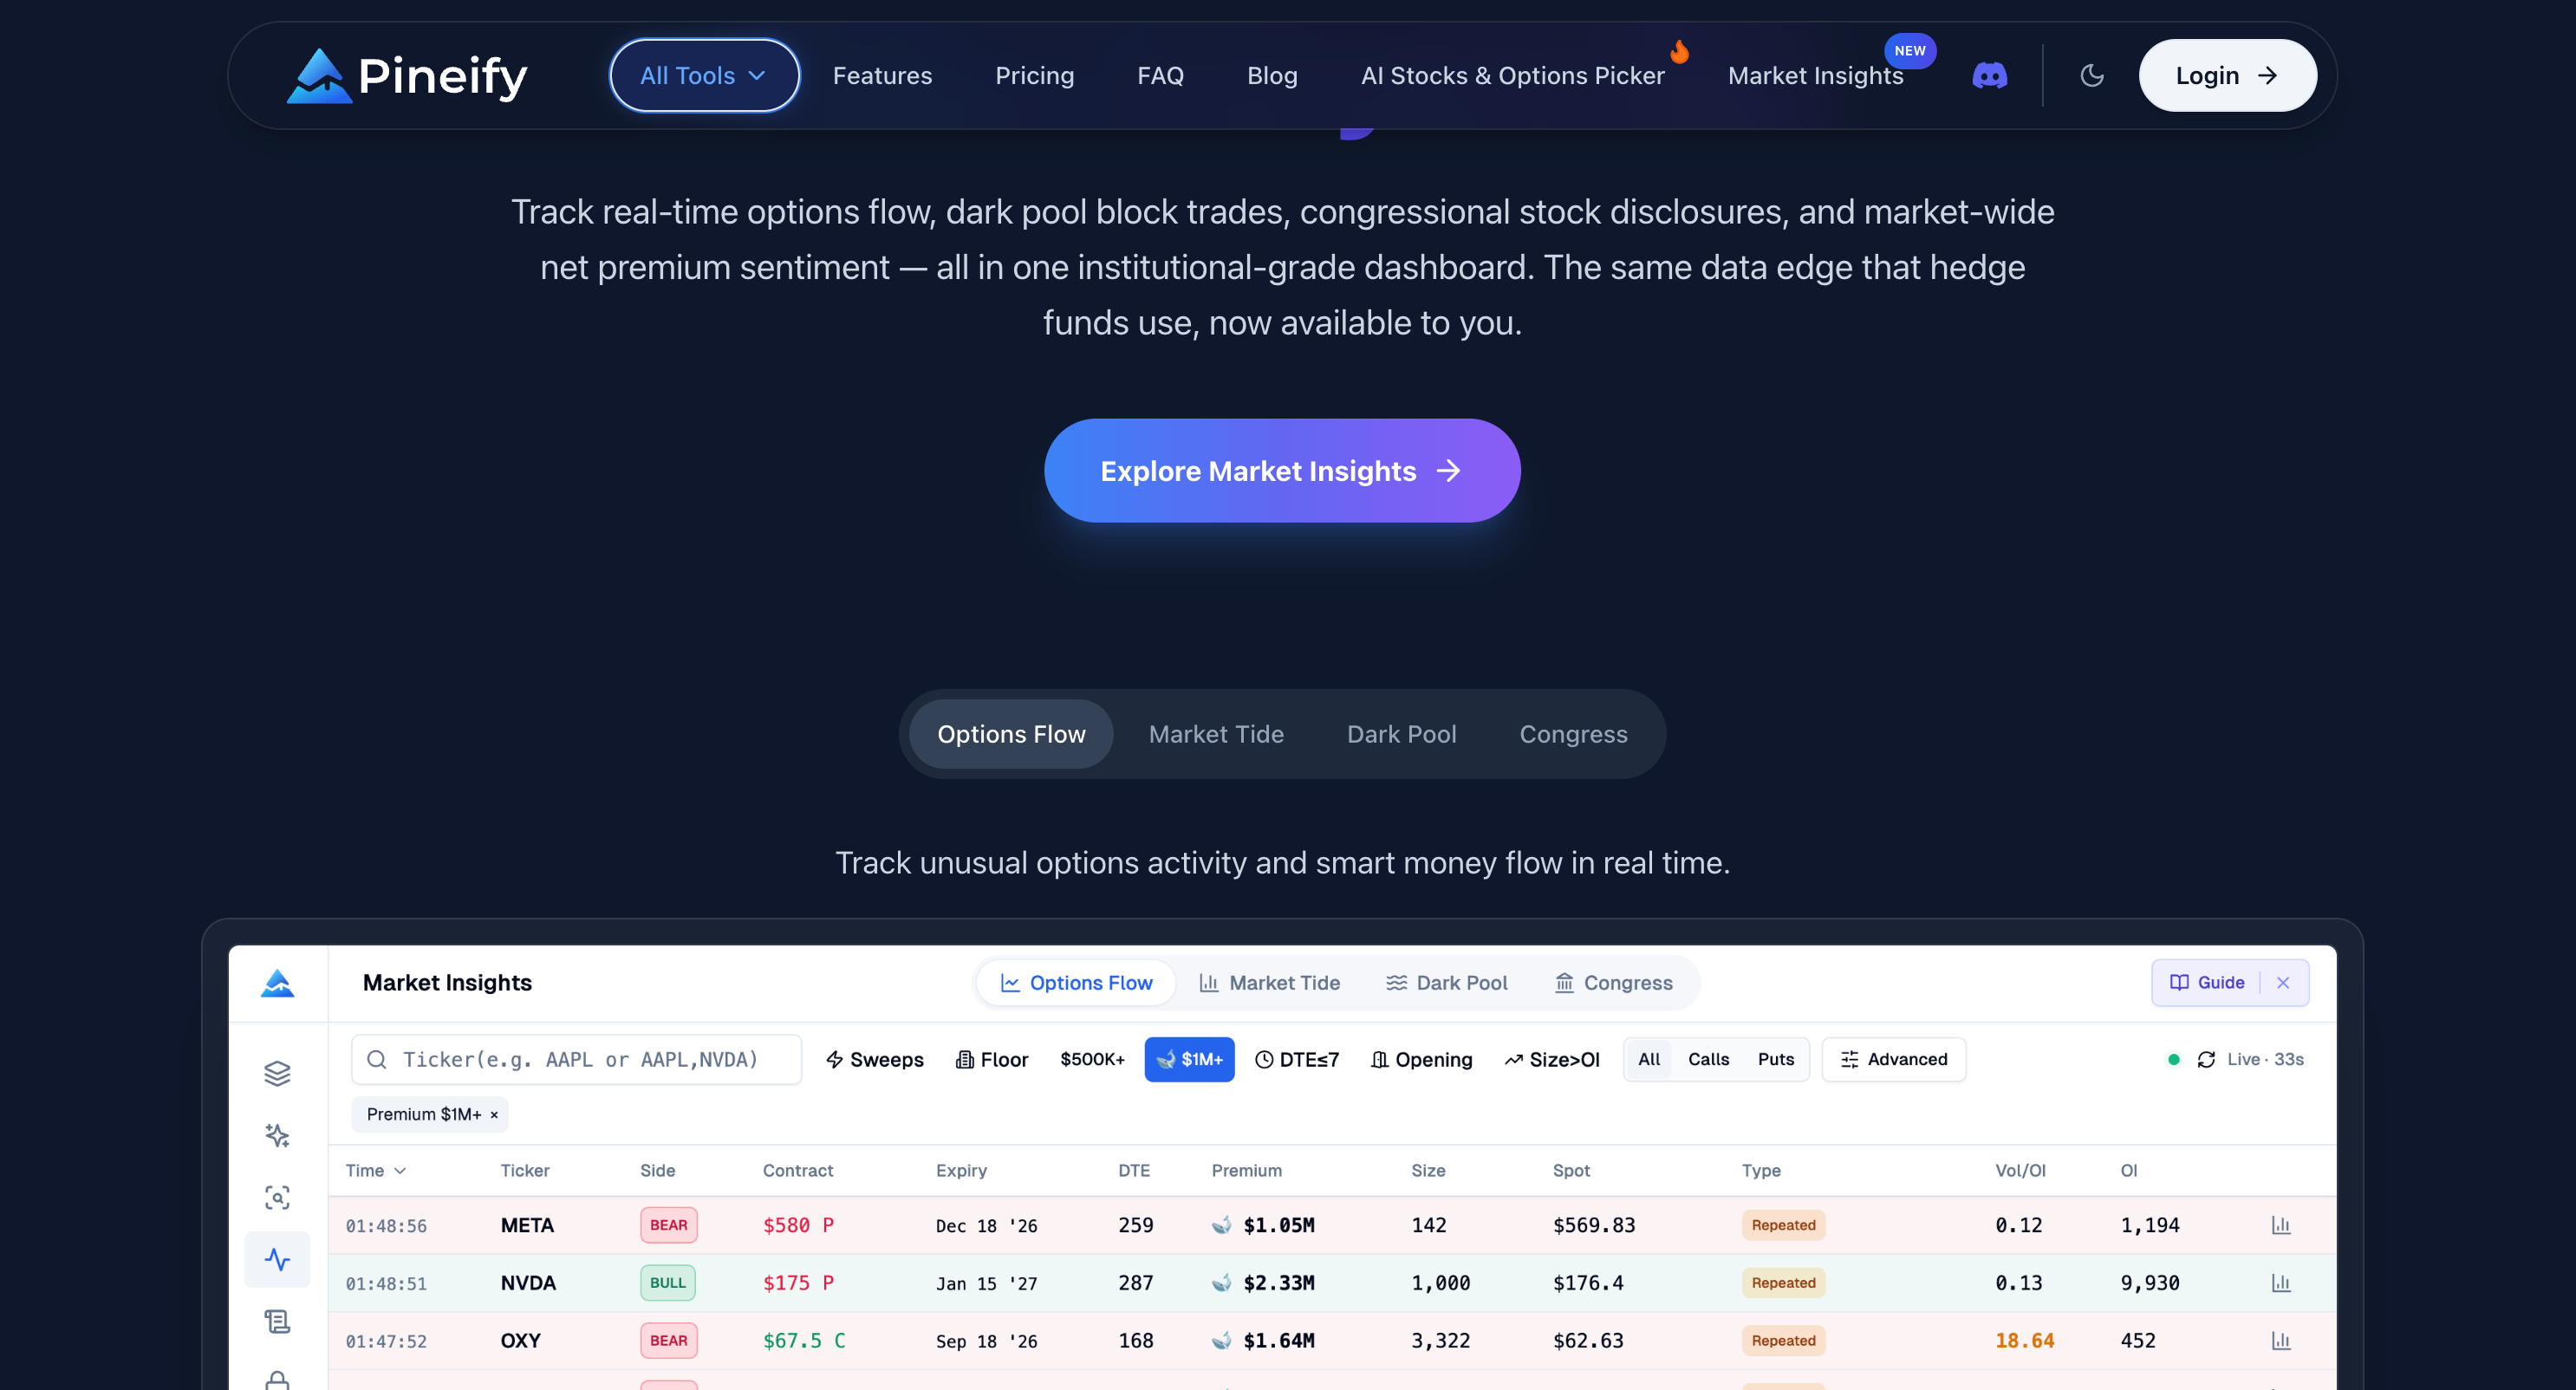
Pineify Market Insights supports ticker and options-flow filters. The current options-flow screen refreshes on a 60-second polling interval; that does not establish sub-second delivery or coverage of every exchange event.
Its sentiment calculation uses the share of reported premium associated with the ask or bid. When ask-side premium exceeds 60% of total premium, calls are classified bullish and puts bearish. When bid-side premium exceeds 60%, calls are classified bearish and puts bullish. Other cases, including nonpositive total premium, are neutral. This is a product heuristic, not a verified description of the trader's net exposure.
Select NVDA and a defined date or observation window. Compare expiry groups and contract types separately. Keep the raw premium and volume fields alongside the label so a color does not replace the evidence.

Put Greeks and earnings in context
OIC describes delta as an estimate of an option premium's response to a one-point underlying move with other conditions held constant. A 0.70 delta is not proof of institutional conviction or a fixed one-for-one relationship with the stock. Delta changes, and volatility, time, and other inputs affect the option simultaneously.
Around an earnings event, separate the announcement date, the selected expiry, and the observation time. A long option can lose value after an event even when the stock moves in the anticipated direction if the move is insufficient or implied volatility falls. Do not infer a profitable trade from a correctly guessed stock direction.
An observation log can include the contract identifier, quoted spread, premium, sentiment rule, event timing, and alternative explanations. Record the intended review horizon before inspecting subsequent prices. This makes failed as well as successful hypotheses visible.
Use dark pool and Market Tide data as context
Reported off-exchange equity prints do not identify the owner behind an options transaction. Pineify estimates dark pool side from the supplied quote midpoint, and its size classes use notional amounts. Matching a call-flow label with a buy-tagged equity print does not prove one institution is accumulating both instruments.
Market Tide aggregates reported option-premium measures. Pineify's directional measure uses net call premium minus net put premium. Treat that as a separate market sample with its own timestamps and coverage, not proof that NVDA must follow the aggregate.
A practical NVDA review sequence
- Choose a time window and record the data timestamp.
- Filter NVDA, then separate calls and puts by expiry and strike.
- Inspect premium, volume, open interest, quote context, and any multi-leg indicators.
- Note scheduled events and plausible hedging or closing explanations.
- Compare the observation with a predefined hypothesis and later outcomes, including costs.
Market Insights currently requires Expert or higher. Verify current access and available fields in the product. This workflow does not promise custom push alerts, a complete Greeks record for every print, or a direct connection from Market Insights into a Pine strategy.
Does an NVDA call sweep mean the stock will rise?
No. It describes reported execution activity. The trade can be hedged, closing, or part of a spread, and the feed does not disclose the complete position.
Does volume above open interest prove new positions?
No. Open interest depends on both sides of each transaction and is distinct from the day's trading volume.
What premium threshold identifies institutions?
No fixed threshold establishes identity. Use thresholds to control the sample and document their effect on the observations.
Can flow predict NVIDIA earnings?
Flow can describe positioning-related activity before an event, but it does not reveal the result or guarantee a profitable options trade.