How to Read Options Flow: Trade Data and Its Limits

Options flow is a record of option executions, often filtered by size, premium, or unusual volume. It can help identify contracts worth investigating. A trade print alone does not reveal the trader's identity, whether the position is opening or closing, or the risk of the rest of that trader's portfolio.
Read the contract before interpreting sentiment
Record the underlying, call or put, strike, expiration, execution time, size, price, and contract multiplier. Premium is price multiplied by contracts and the applicable multiplier; adjusted contracts can differ from the familiar 100-share convention. Confirm the data source, delay, and whether the feed contains corrections or multi-leg condition codes.
For an illustrative standard contract with a multiplier of 100, 200 contracts executed at $2.50 represent $50,000 of premium. That amount is not the buyer's profit, the underlying exposure, or proof that an institution initiated the trade.
Compare the execution with contemporaneous quotes
An execution near the ask may be classified as buyer-initiated, while one near the bid may be classified as seller-initiated. This is an inference from quotes, not an identification of the participant or intent. Midpoint executions, stale quotes, fast markets, and complex orders can make classification uncertain. See the Options Industry Council's bid and ask explanation.
| Observation | What to investigate | What it cannot establish |
|---|---|---|
| Large call print near the ask | Quote timing, opening/closing information, related legs | A guaranteed bullish stock forecast |
| Large put print | Purchase versus sale, hedge or standalone position | That the buyer expects an immediate decline |
| Sweep classification | Provider definition and linked executions | Insider knowledge or a guaranteed breakout |
| Volume above prior open interest | Repeated turnover and next reported open interest | That every trade created a new position |
Every execution has both a buyer and seller. A bought call can close a short call; a bought put can hedge stock. Expiration constrains the contract's life, but does not tell you how long its holder intends to keep it.
Separate volume from open interest
Volume counts trading during a period. Open interest counts outstanding contracts, affected by whether both sides open, both close, or one opens while the other closes. Intraday volume is therefore not interchangeable with the change in open interest. The OIC explanation of open interest describes these combinations.
An unusual-activity filter is useful only with its definition: relative to which lookback, strike, expiration, and time of day? Compare like with like. Earnings, expiration rolls, and index rebalances can create exceptional volume without providing a new directional signal.
Treat aggregate premium measures as model outputs
A dashboard may aggregate classified call and put premium into a sentiment series. Read its methodology before comparing values across providers: bid/ask treatment, trade exclusions, coverage, and update frequency affect the result. A net-premium measure is not inherently more accurate than implied volatility or a put/call ratio; each measures something different.
Testing a hypothesis requires a timestamped signal definition and an outcome period chosen before observing the result. Save all qualifying observations, including failed signals, and account for spreads, fees, and option time decay. Several indicators derived from the same underlying trades are not independent confirmations.
Dark-pool prints and congressional disclosures have different limits
Off-exchange stock trading includes ATS and non-ATS activity; the entire category should not be labeled dark pools. FINRA explains that listed-stock ATS executions are reported and appear on the consolidated tape. Public prints do not reveal a fund's full holdings or establish future support and resistance. See FINRA's trading-venue explanation.
Congressional disclosures are delayed records, not realtime positions or evidence of privileged knowledge. For reportable House transactions, the deadline is generally the earlier of 30 days after awareness or 45 days after the transaction. Check the transaction date, disclosure date, owner, amount range, and amendments. The House Ethics financial-disclosure guidance is the primary reference; coverage and exclusions matter when building a dataset.
Use a dashboard to organize the evidence
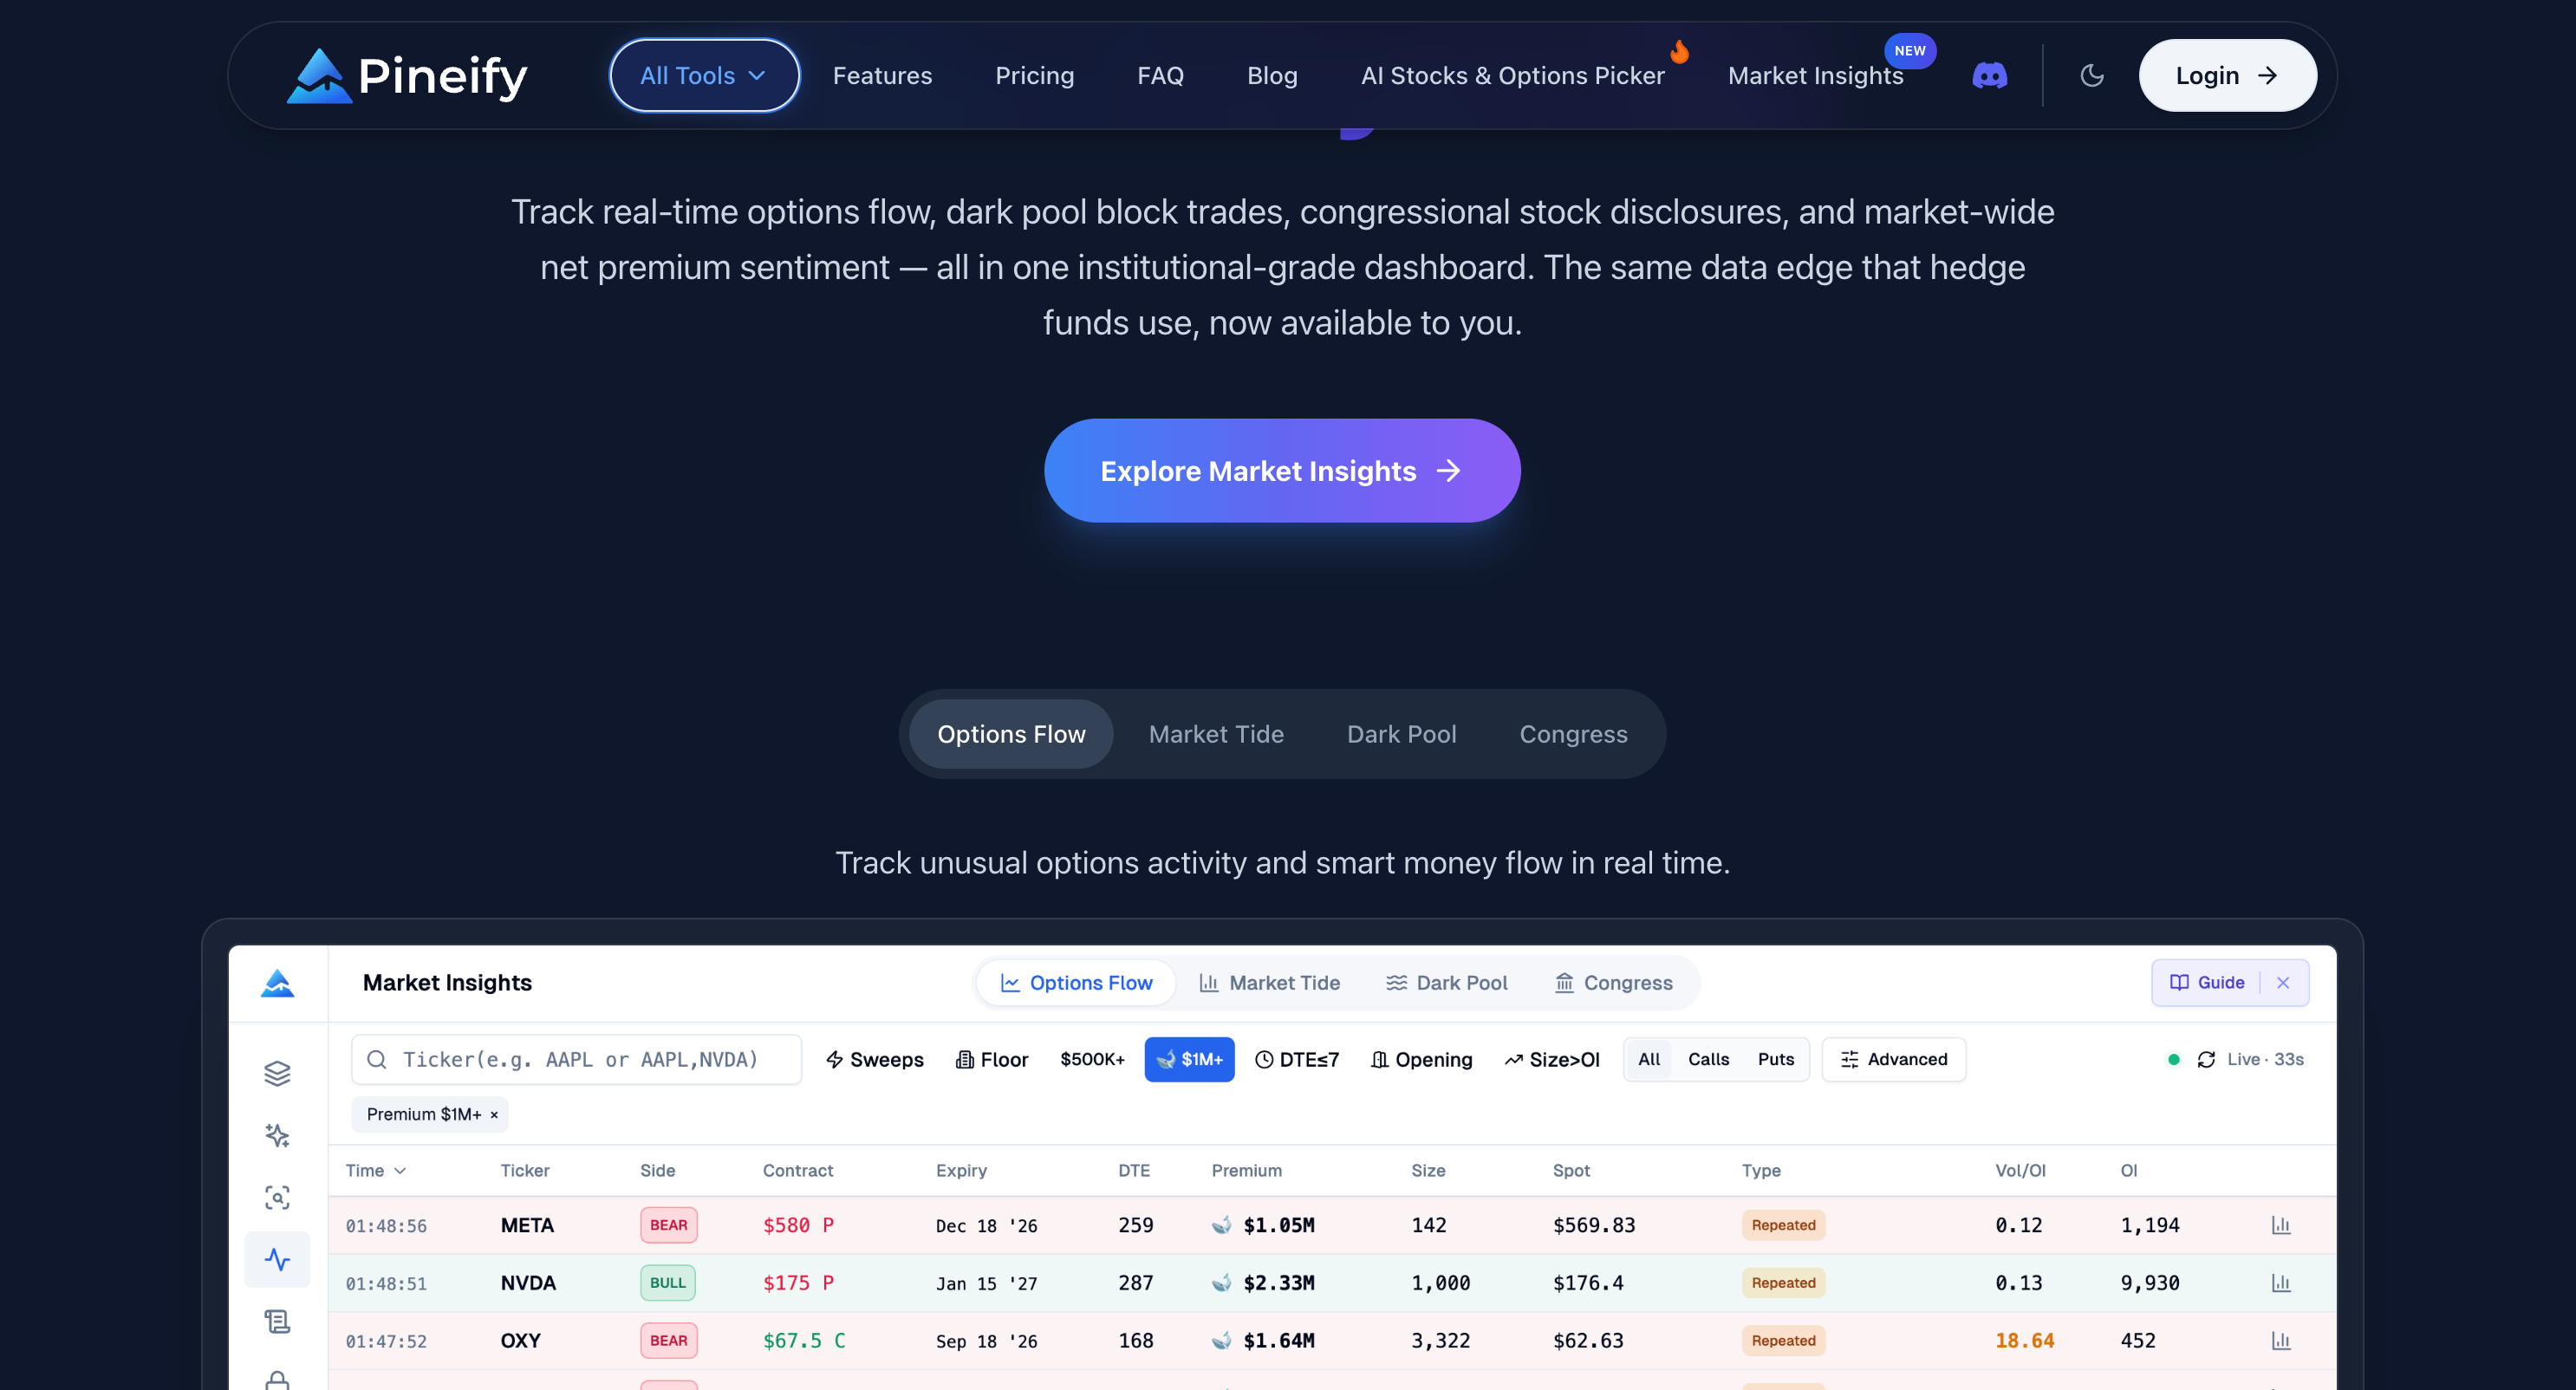
Pineify Market Insights provides research views for options flow, Market Tide, dark-pool activity, and congressional disclosures. Check the timestamps and definitions in each view. This article does not establish a latency benchmark, capture of every trade, or a return advantage for those features.

Start with one underlying and a written observation log: contract details, quote context, classifier uncertainty, relevant events, and the subsequent outcome. Investigate the contract's liquidity and risk before considering a trade. Large or unusual flow can supply a research question; it cannot supply the missing portfolio context or ensure a profitable answer.