Option Flow Data: How to Read Trades, Sentiment Tags, and Their Limits

Options flow data describes reported option transactions or provider-generated alerts about them. It can help identify contracts for further research, but a large call trade does not reveal the trader's identity, opening or closing intent, or full portfolio exposure. Read the contract, execution context, and timestamp before interpreting a sentiment label.
Read the fields without adding a story
| Field | What it establishes | What it does not establish |
|---|---|---|
| Underlying and contract | The instrument, call/put, strike, and expiration | The trader's entire position |
| Strike | The contract's exercise price | A predicted stock-price target |
| Size | Number of contracts reported | Whether the trader is an institution |
| Premium | Option price times size and applicable multiplier | Conviction, expected profit, or directional exposure |
| Bid/ask-side tag | Provider classification relative to quotes | Certain buyer intent or whether a position is opening |
| Sweep/block label | A reported or inferred execution pattern | Informed trading or a profitable signal |
| Timestamp | A reported event or alert time | The exact moment your screen first received it |
A standard unadjusted equity option commonly represents 100 shares, but adjusted contracts and other products can differ. Use the actual multiplier and deliverable. A hypothetical 500-contract trade at a premium of 2 with multiplier 100 represents 100,000 of premium—not 500 shares and not 100,000 of stock exposure.
Calls can be bought or sold, opened or closed, and combined with other options or stock. A purchased put can hedge a stock position. A call execution near the ask may be consistent with buyer initiation, but stale quotes, spreads, and multi-leg execution complicate that inference. The display cannot normally reveal the beneficial owner's complete portfolio.
Volume above open interest does not prove new buying
Volume counts contracts traded during a period. Open interest measures outstanding contracts after clearing; it is not a continuously updated count of new buyers. The Options Industry Council explains that the effect on open interest depends on whether both counterparties open, both close, or one opens while the other closes.
Repeated transactions in the same contract can generate volume larger than prior open interest without an equally large increase in outstanding positions. Next-day open interest can help investigate aggregate changes, but it still does not assign a specific opening intent to each earlier print. Treat the ratio as an activity filter, not proof of fresh institutional conviction.
“Unusual” also needs a denominator. Compare activity with a defined historical window, similar time of day, and an appropriate contract or underlying universe. There is no universal 100-contract, 500,000-premium, or two-times-volume threshold that identifies informed traders.
Sweeps, blocks, and short-dated contracts
A sweep label can group executions across venues or identify a routing characteristic, depending on the provider. A block describes size or execution structure under the relevant definition. Neither label establishes why the order was placed. A scanner's grouping rules can also cause several prints to represent one underlying order rather than independent evidence.
Expiration affects time decay, sensitivity, exercise, and settlement—not just “urgency.” Cboe reported that SPX 0DTE options accounted for 59% of SPX volume in full-year 2025, with average daily volume of 2.3 million contracts. That is a specific product and period, not the share of all U.S. options. The statistic does not prove that each same-day trade creates directional stock-market pressure. Cboe's 2025 volume release
A correct directional view can still lose money in an option if the move is too small or late, implied volatility falls, or execution costs dominate. Near-expiry contracts can change rapidly; a fixed 1–2% stock pullback is not a universal entry rule.
A practical record-by-record review
- Identify the exact contract. Confirm expiration, strike, type, multiplier, underlying price, and whether the contract is adjusted.
- Check freshness. Compare execution time, alert creation time, receipt time, and the quote used for classification. Preserve the timezone.
- Inspect the execution context. Note bid/ask spread, quote-side classification, multi-leg flags, and whether nearby prints may be related.
- Check activity context. Record the volume and open-interest dates, the relative-volume baseline, and any scheduled event. Do not infer nonpublic information from activity before earnings.
- Write competing explanations. A directional position, a hedge, a closing trade, or one leg of a spread may fit the same record. Mark what cannot be established.
- Define a research rule before observing its outcome. State any chart condition, holding period, exit, position size, and costs. A later price breakout is another observation, not proof of the original trader's intention.
If testing a flow-plus-price rule, compare it with the same price rule without flow. Include alerts that failed, arrived late, or could not be traded at the displayed price. A three-week paper exercise can reveal workflow problems; it is not a standard proof of profitability.
Market Tide, dark-pool prints, and disclosures are different datasets
Market Tide summarizes provider-classified net option premium. Unusual Whales' net-flow explanation distinguishes ask-side premium from bid-side premium rather than simply adding every call as bullish and every put as bearish. Pineify's current directional total subtracts net put premium from net call premium. This is a derived measure, not a direct count of bullish institutions or proof of sector capital rotation.
Dark-pool or off-exchange stock prints concern equity transactions, not option executions. FINRA explains that listed-stock trades on alternative trading systems are reported and published on the consolidated tape. A print records an execution; it does not show a standing order that will defend that price. Not every off-exchange trade is a dark-pool trade. FINRA's venue explanation
Congressional disclosures are delayed reports. House guidance requires covered transactions to be reported within 30 days of awareness or 45 days of the transaction, whichever is earlier. Filing data must be evaluated using the date it became available, with the original disclosure checked for ownership and value ranges. A cluster of filings is not evidence of insider knowledge or a guaranteed trading edge. House financial-disclosure guidance
Using Pineify Market Insights
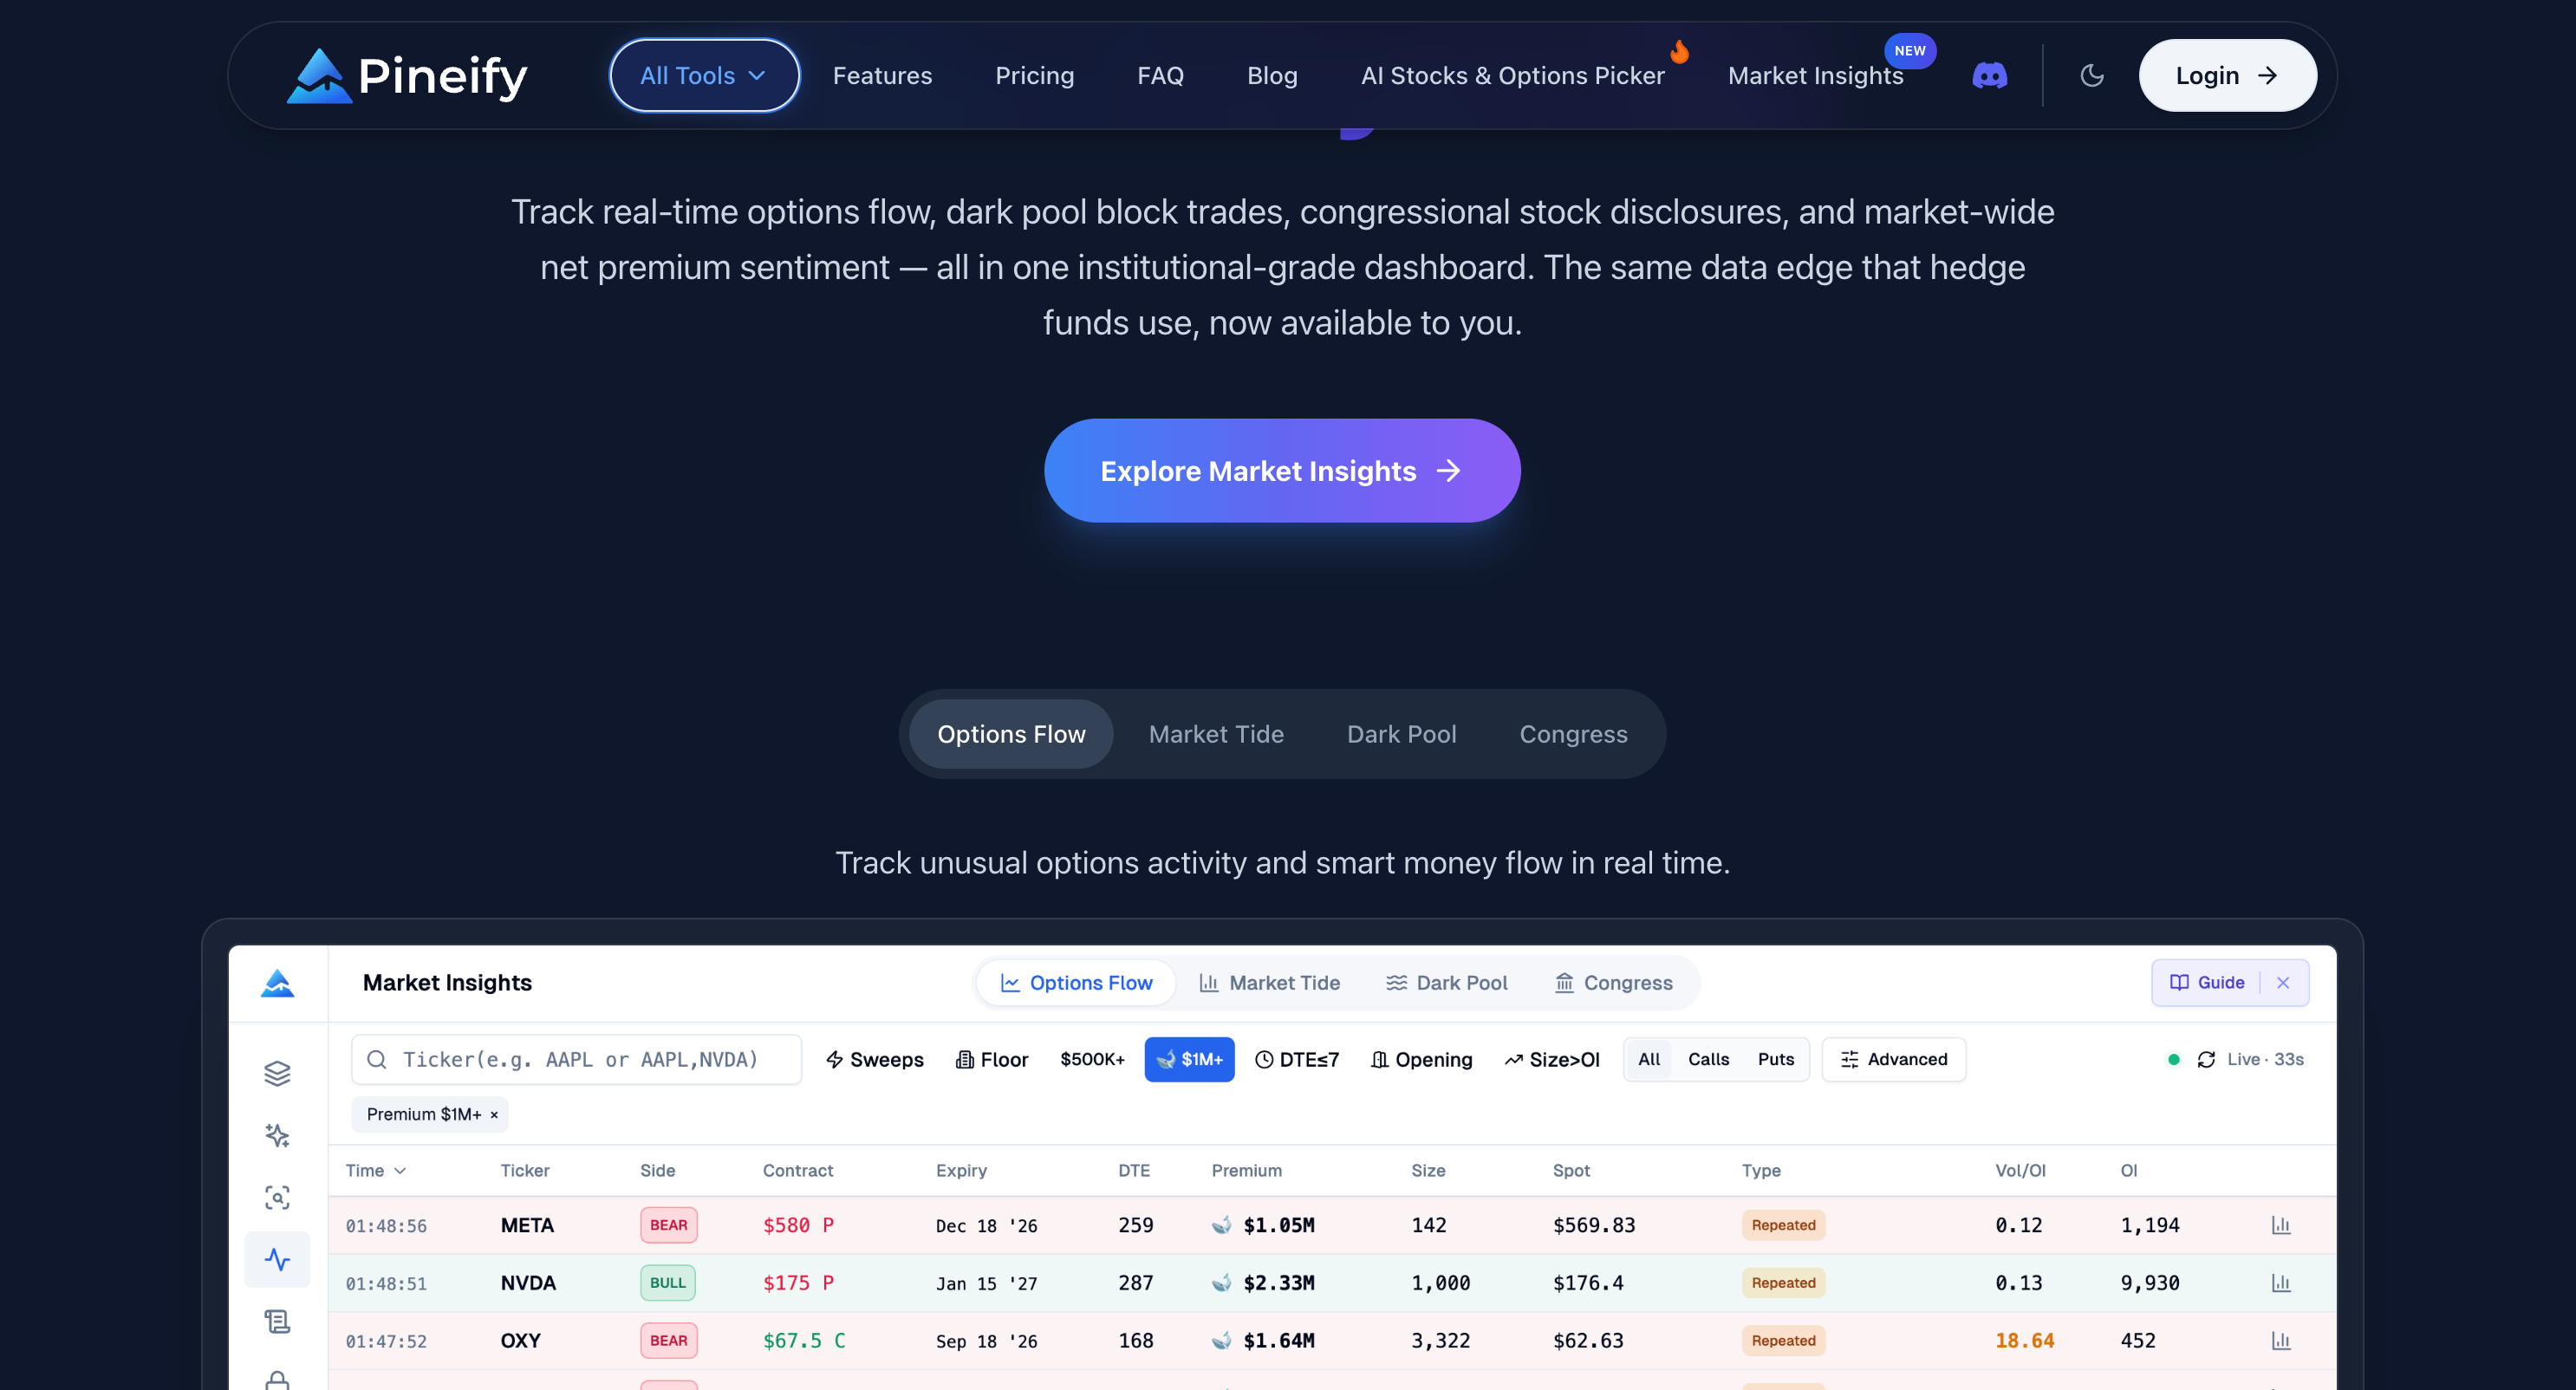
Pineify Market Insights provides options-flow, Market Tide, dark-pool, and Congress views. The current options-flow UI requests a limited alert list—100 by default—and uses 60-second polling while active, with manual refresh. Hidden-page polling pauses. These are application refresh settings, not a guarantee of exchange-to-screen latency or complete coverage of every trade.
The current flow sentiment label uses option type and the fraction of reported premium assigned to the ask or bid. A ratio above 60% produces a directional classification; otherwise it can remain neutral. That rule is a heuristic and does not verify opening intent. Inspect the underlying fields and last-updated state instead of treating the label as an investment recommendation.

Research, Pine code generation, and journal records are separate workflows. A dashboard alert does not automatically become an executable TradingView strategy or a broker order. No verified 50,000-trades-per-day throughput, personal TSLA/NVDA calls, or provider-wide return benchmark is presented here.
Does a large call sweep prove institutional buying?
No. Size and execution pattern do not identify the owner, opening intent, or other portfolio legs. The quote-side tag is an inference with limitations.
Does volume above open interest mean new positions are flooding in?
No. Intraday volume and outstanding contracts measure different things. Repeated turnover and opening/closing combinations can produce a high ratio without a matching rise in open interest.
Is the strike price the buyer's target?
It is the contract's exercise price. It does not establish a forecast, and an option's profitability also depends on premium, timing, volatility, and costs.
Is Pineify flow an instantaneous feed of every option trade?
The reviewed interface displays a limited alert list and polls while active. Check timestamps, filters, provider coverage, and entitlements; no zero-delay or all-trades guarantee is made here.